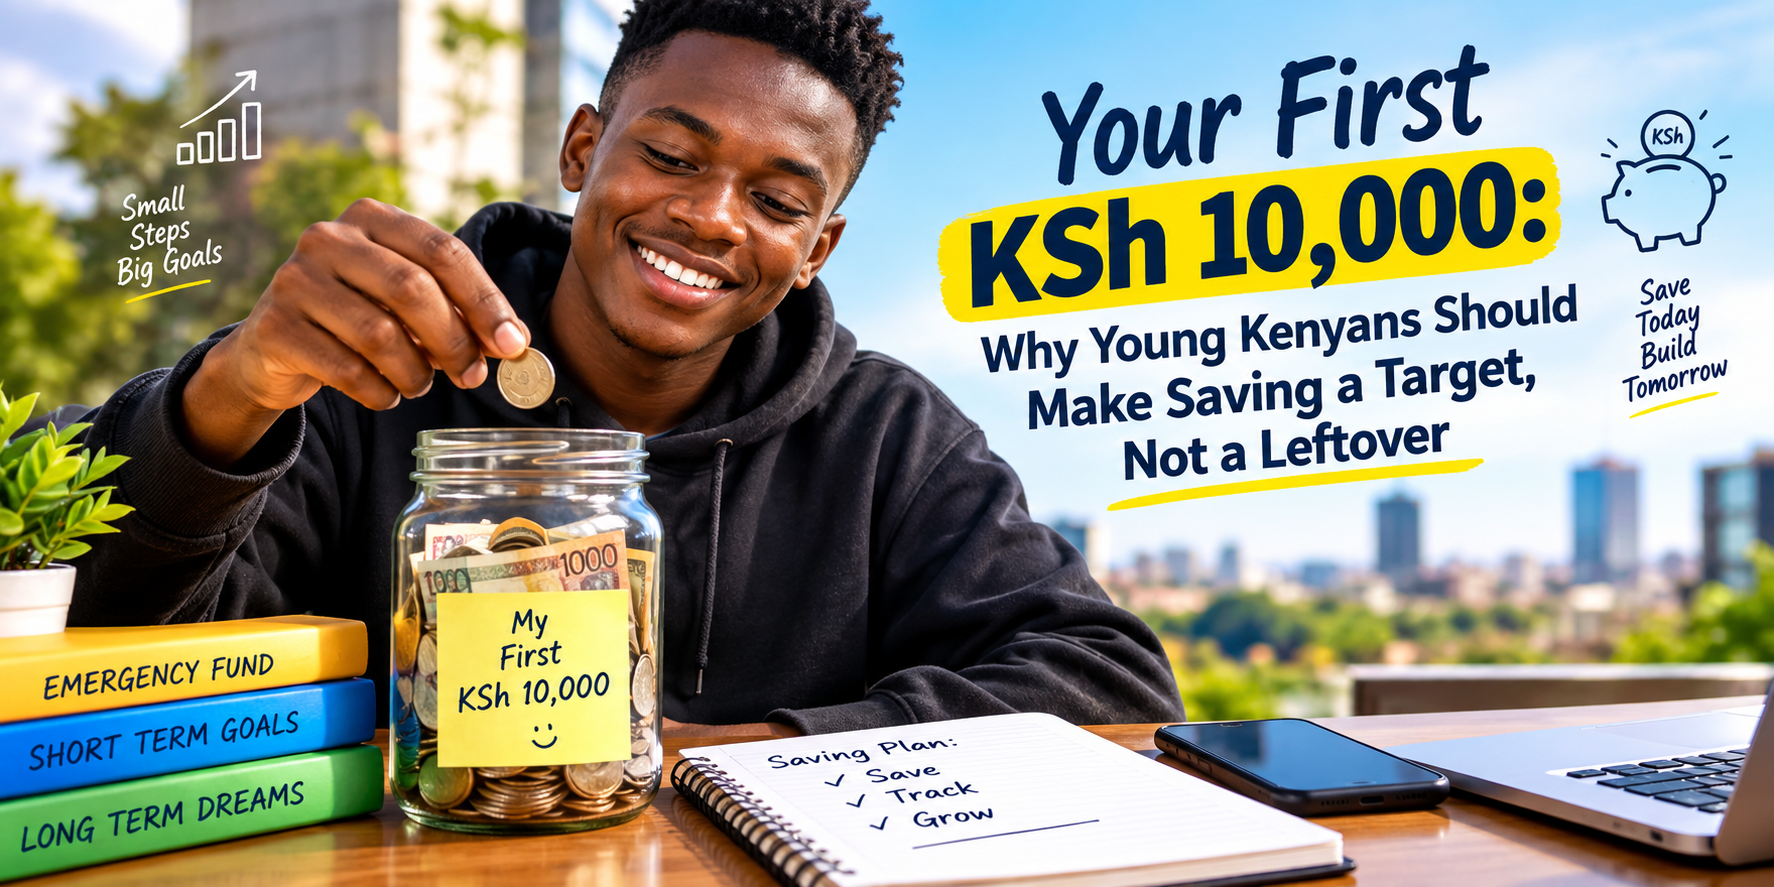
For many young people, saving starts with a familiar promise: “I’ll save whatever remains at the end of the month.”
The problem is that there is often nothing left.
Kenya’s financial-health picture shows why building a savings habit matters. The 2024 FinAccess Household Survey found that only 18.3% of adults were financially healthy, meaning they could manage daily needs, cope with financial shocks and invest toward future goals.
For a young person earning their first salary, running a small business or depending on irregular income, one practical response is to turn saving into a specific target.
Start with KSh 10,000
You don't need to begin with KSh 100,000.
Set your first target at KSh 10,000.
If you save:
- KSh 250 a week, you can reach KSh 13,000 in a year.
- KSh 500 a week, you can reach KSh 26,000 in a year.
- KSh 1,000 a month, you can reach KSh 12,000 in a year.
- KSh 2,000 a month, you can reach KSh 24,000 in a year.
The important part isn't the size of your first target. It is creating a system that makes saving consistent.
Why waiting until month-end doesn't work
When savings come last, spending usually comes first.
Rent gets paid. Food is bought. Transport takes its share. Data bundles, entertainment and unexpected expenses follow.
By the end of the month, saving becomes difficult.
Instead, save first and spend what remains.
Even if it is only KSh 100 or KSh 200, setting the money aside immediately after receiving income can help turn saving into a habit.
Separate your savings goals
Not all savings should have the same purpose.
You can divide your money into three simple categories.
Emergency savings — money for unexpected expenses.
Short-term savings — money for something you expect to buy or pay for within a few months.
Long-term savings — money intended for future goals and wealth-building.
This makes it easier to understand why you are saving instead of simply accumulating money without a plan.
Digital finance makes saving easier—but discipline still matters
Kenya's formal financial access reached 84.8% in 2024, according to the Central Bank of Kenya. Digital financial services have played an important role in expanding access.
For young people, this means saving can be more convenient than it was for previous generations.
But convenience does not automatically create good financial habits.
Having a mobile wallet, bank account or savings product does not mean money will accumulate unless you deliberately put some of your income aside.
The biggest challenge is often not finding somewhere to save.
It is leaving the money there.
Make KSh 10,000 your first milestone
Try turning saving into a personal challenge.
Start with a target of KSh 10,000.
Choose an amount you can realistically save every week or month. Track your progress and avoid withdrawing the money for ordinary spending.
Once you reach KSh 10,000, create another target.
Perhaps KSh 25,000.
Then KSh 50,000.
Over time, these small milestones can become a much larger financial cushion.
The objective isn't to become wealthy overnight.
It is to develop the habit of paying yourself first.
The real value of your first KSh 10,000
Your first KSh 10,000 represents more than money in an account.
It represents financial breathing room.
An unexpected expense doesn't automatically have to become a loan. A temporary drop in income doesn't have to immediately become a crisis. And a future opportunity may become easier to pursue because you have money available.
For young Kenyans, financial independence doesn't necessarily begin with a huge salary.
Sometimes, it begins with the decision to keep the first KSh 100 instead of spending it.
Your first KSh 10,000 won't solve every financial problem—but building the habit of reaching it can change the way you manage money for years to come.
#FTLuma #FinancialLiteracy #YouthFinance #SavingMoney #MoneyManagement #KSh10000Challenge #PersonalFinance #Kenya #FinancialGoals #SmartMoney #SaveMoney


💬 Discussion (0)
No comments yet. Be the first to share your thoughts!
Leave a Response